Macroeconomic/ geopolitical developments
- US stocks declined during the holiday shortened week, with the S&P 500 falling 0.80%, the Nasdaq Composite dropping 0.66%, and the Dow Jones Industrial Average declining 1.57%. Smaller companies were hit hardest, while energy was the strongest performing sector and healthcare recorded the steepest decline.
- Oil prices surged as renewed US-Iran hostilities and threats to regional energy infrastructure raised concerns over global supply disruptions. WTI briefly rose above $100 a barrel, while uncertainty surrounding the Strait of Hormuz left oil markets vulnerable to further volatility.
- US Treasury yields climbed sharply, with the 10 year yield approaching 5% and the 30 year yield reaching levels close to a two decade high. Higher government debt issuance, fiscal concerns, and inflationary pressures increased borrowing costs and placed further pressure on equities.
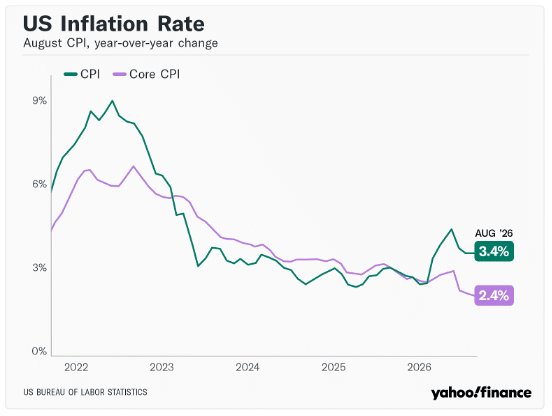
- US headline CPI rose 0.4% in August, leaving annual inflation unchanged at 3.4%, while core CPI increased 0.3% month over month and annual core inflation eased to 2.4%. Persistent price pressures, higher gasoline costs, and a resilient labor market increased expectations of a Federal Reserve rate hike to around 85% to 90%.
- The Federal Reserve’s September meeting will be closely watched for its interest rate decision, updated projections, and Chair Kevin Warsh’s comments. Investors will assess whether any rate hike is a one off move or the beginning of a more sustained tightening cycle.
Global financial market developments
- US and global equity averages were lower.
- US and European bond were notably higher on the week
- The US Dollar Index was little changed on the week.
- Gold futures were slightly lower for the week
- Oil futures prices rallied through the week to a multi-month peak.
Key this week
Central Bank Watch: It is a busy week for central bank activity, the main release will be the Federal Reserve Interest Rate Decision, Monetary Policy Statement and Press Conference on Wednesday. Some other releases of note are the Bank of England Interest Rate Decision, Monetary Policy Statement and Minutes on Thursday and the Bank of Japan Interest Rate Decision, Monetary Policy Statement and Press Conference on Friday.
Macro Data Watch: Macro data is light this week, the main macro data releases to look out for are the Chinese CPI and UK Employment reports on Tuesday and the US Retail Sales and UK CPI on Wednesday.
| Date | Major Macro Data |
| 09/14/2026 | Canadian CPI |
| 09/15/2026 | Chinese Retail Sales and Industrial Production; UK Employment reports; US NY Empire State Manufacturing Index |
| 09/16/2026 | Japanese Trade report; UK CPI, PPI and RPI; EU Industrial Production; US Retail Sales; Fed Interest Rate Decision, Monetary Policy Statement and Press Conference |
| 09/17/2026 | EU HICP; BoE Interest Rate Decision, Monetary Policy Statement and Minutes; US Building Permits, Housing Starts, Initial Jobless Claims, Fed Manufacturing Survey and Pending Home Sales |
| 09/18/2026 | Japanese CPI; BoJ Interest Rate Decision, Monetary Policy Statement and Press Conference; German PPI; Eurogroup Meeting; UK Retail Sales; US Industrial Production |
