Macroeconomic/ geopolitical developments
- US stock markets ended the week higher, with the S&P 500 gaining 1.15%, the Dow Jones Industrial Average rising 0.93% and the Nasdaq Composite advancing 0.64%, despite midweek volatility. The S&P 500 and Nasdaq reached record highs, while utilities and consumer defense stocks led sector gains and smaller companies continued to lag.
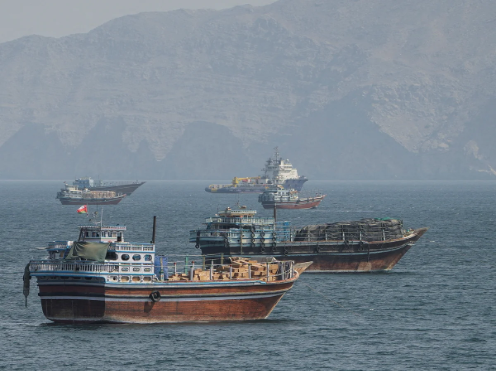
- Oil prices moved higher amid renewed attacks on shipping around the Strait of Hormuz, with Brent crude briefly exceeding $105 a barrel. Hurricane Isaias added to supply concerns, keeping geopolitical risks and potential energy disruptions firmly in focus.
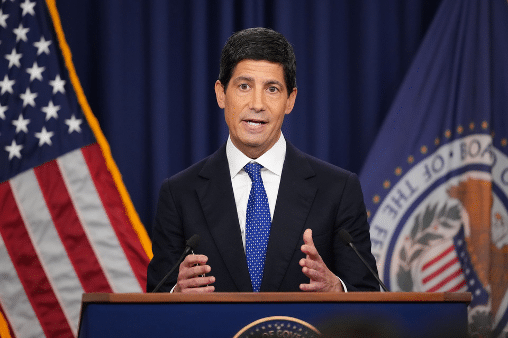
- Federal Reserve Minutes indicated that most policymakers saw another rate increase before year end as appropriate, with inflation risks remaining a concern. Treasury yields eased slightly from recent highs, as softer employment data tempered expectations of an immediate October rate hike.
- Investors will focus on the start of the third quarter earnings season, particularly results from major US banks and semiconductor companies for clues on financial conditions and AI related demand. Wednesday’s US CPI report is the key economic release, with inflation data likely to influence expectations for the Federal Reserve’s next policy decision.
Global financial market developments
- US and global equity averages were higher.
- US and European bond yields were little changed on the week.
- The US Dollar Index was little changed, hovering near a multi-month high.
- Gold futures were little changed, hovering near a multi-week low.
- Oil futures prices were slightly higher on the week.
Key this week
Central Bank Watch: It is a relatively quiet week on the central bank front, with the only major release being the RBA Meeting Minutes on Tuesday. Instead, investor focus will be on speeches from officials at the Fed, ECB, BoE and BoC for any fresh signals on the interest rate outlook.
Macro Data Watch: The main macro data release this week is the US CPI on Wednesday. Some other releases of note are the German HICP on Tuesday, Chinese CPI on Wednesday, US Retail Sales and PPI both on Thursday.
Earnings Watch: The Q3 US earning season kicks off this week with major US banks reporting alongside J&J, ASML and Taiwan Semiconductor.
| Date | Major Macro Data |
| 10/12/2026 | Nothing of note |
| 10/13/2026 | UK Retail Sales; RBA Meeting Minutes; German HICP; US Existing Home Sales Change and Monthly Budget Statement |
| 10/14/2026 | Chinese CPI, PPI and Trade Reports; US CPI and Fed Beige Book |
| 10/15/2026 | UK GDP, Industrial Production and Manufacturing Production; EU Industrial Production; US Retail Sales, PPI, Initial Jobless Claims; NY Empire State Manufacturing Index and Philadelphia Fed Manufacturing Survey |
| 10/16/2026 | US Industrial Production; EU HICP |
| Date | Major Earnings Data |
| 10/12/2026 | Louis Vuitton; Progressive |
| 10/13/2026 | JPMorgan; J&J; UnitedHealth; Goldman Sachs; Wells Fargo&Co; Citigroup; Rio Tinto ADR; Domino’s Pizza |
| 10/14/2026 | ASML ADR; Bank of America; Morgan Stanley; BlackRock |
| 10/15/2026 | Taiwan Semiconductor ADR; Charles Schwab; Interactive Brokers; Prologis |
| 10/16/2026 | Schneider Electric |
