Macroeconomic/ geopolitical developments
- The S&P 500 gained 2.51%, the Nasdaq rose 2.27%, and the Dow Jones advanced 2.10% over the week. The recovery was supported by strength across several sectors, particularly energy and industrials, although concerns about inflation and rising Treasury yields kept markets volatile.
- AI stocks recovered as strong results from Taiwan Semiconductor Manufacturing and CoreWeave helped restore confidence in the sector. Nvidia fell approximately 13% following Jensen Huang’s resignation and future leadership uncertainty, but the wider semiconductor index gained around 8%, highlighting the resilience of the broader AI trade.
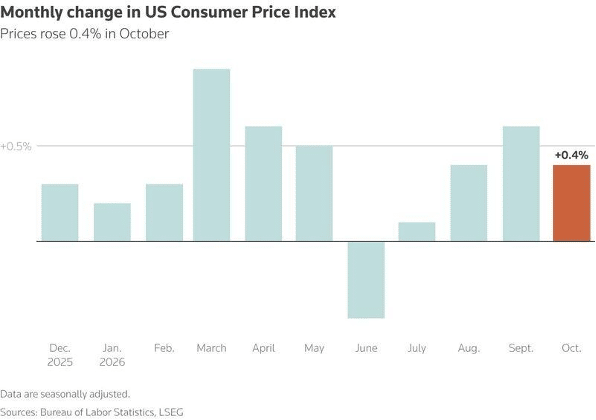
- October CPI rose 0.4% month on month, above the 0.3% forecast, while core inflation also exceeded expectations at 0.3%. The stronger figures increased concerns about persistent price pressures and reinforced expectations of further Federal Reserve rate increases.
- The 10-year Treasury yield climbed from 4.86% to 5.15%, while the two-year yield increased from 4.51% to 4.88%. Stronger inflation data and hawkish comments from Fed officials pushed rate expectations higher, creating further pressure for bond prices and equity valuations.
- Nvidia’s third-quarter results on Tuesday will be closely watched, with investors focusing on AI demand, profit margins and its future outlook. US Retail Sales on Tuesday and the Fed’s October Meeting Minutes on Wednesday will also provide important clues about consumer strength and the outlook for interest rates.
Global financial market developments
- US and global equity averages were higher, rebounding after multi-week losses.
- US and European bond were notably higher on the week
- The US Dollar Index surged to a multi-month high.
- Gold futures plunged to a multi-month low.
- Oil futures prices rallied through the week, before a Friday setback.
Key this week
Central Bank Watch: It is a busier week for central bank activity, the main release will be the Federal Open Market Committee Minutes on Wednesday. Some other releases of note are the Reserve Bank of Australia Meeting Minutes on Tuesday and People’s Bank of China Interest Rate Decision on Friday.
Macro Data Watch: The main macro data release this week is US Retail Sales on Tuesday. Some other releases of note are Canadian CPI on Monday, UK Employment Reports on Tuesday and UK CPI on Wednesday.
Earnings Watch: The final releases from the Q3 US earning season come out this week, with the main release being Nvidia on Tuesday. Some other releases of note are Home Depot, Walt Disney, Target and Walmart.
| Date | Major Macro Data |
| 11/16/2026 | Japanese GDP; Chinese Industrial Production and Retail Sales; EU Industrial Production; Canadian CPI |
| 11/17/2026 | RBA Meeting Minutes; UK Employment Reports; US Retail Sales and Industrial Production |
| 11/18/2026 | Japanese Trade Reports; UK CPI, PPI and RPI; EU HICP; US Building Permits, Housing Starts and Pending Home Sales; FOMC Minutes |
| 11/19/2026 | German Buba Monthly Report; US Initial Jobless Claims |
| 11/20/2026 | Japanese CPI; UK Consumer Confidence and Retail Sales; PBoC Interest Rate Decision; German PPI; Canadian Retail Sales; EU Consumer Confidence; US Michigan Consumer Sentiment Index and Consumer Inflation Expectations |
| Date | Major Earnings Data |
| 11/16/2026 | Nothing of note |
| 11/17/2026 | Nvidia; Home Depot; Walt Disney |
| 11/18/2026 | Palo Alto Networks; TJX; Lowe’s; Target |
| 11/19/2026 | Walmart; PDD Holdings DRC; Intuit |
| 11/20/2026 | Nothing of note |
