Macroeconomic/ geopolitical developments
- US stocks ended the week mixed, with the Nasdaq Composite falling 4.48% and the S&P 500 declining 1.95%, while the Dow Jones gained 0.67%. Concerns over AI investment costs and future returns weighed on technology shares, prompting investors to favor more defensive sectors and value stocks.
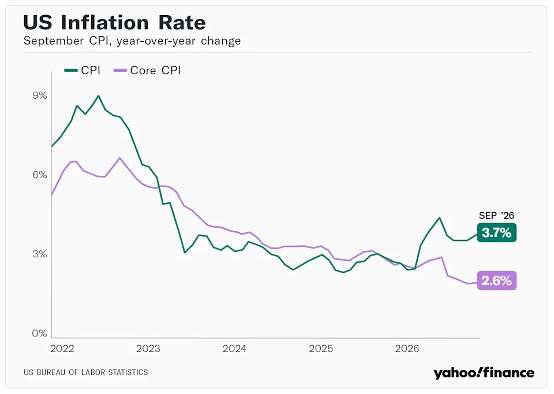
- September CPI rose to 3.7% annually, above expectations, while PPI also exceeded forecasts, increasing pressure on businesses and consumers. The stronger data heightened uncertainty over the Federal Reserve’s next move and the possibility of further interest rate increases.
- Escalating tensions involving Iran and risks to shipping through the Strait of Hormuz pushed oil prices higher, with Brent crude briefly reaching $110 a barrel. Supply disruptions and falling US crude inventories added to inflation concerns, keeping energy prices firmly in focus.
- US Treasury yields fell despite hotter than expected inflation, with the 10 year yield declining to 5.09% and the two year yield to 4.74%. Investors moved towards safer assets amid technology market volatility, although borrowing costs remain elevated and markets remain sensitive to further economic data.
- Major US bank results were mixed, with all six leading bank stocks falling after reporting, while TSMC delivered record quarterly profit supported by strong AI chip demand. This week, investors will focus on results from Meta, Tesla and other major companies, alongside US Flash PMI surveys, Jobless Claims and Consumer Sentiment for clues on economic momentum and inflation.
Global financial market developments
- US and global equity averages were lower.
- US and European bond yields were slightly lower on the week
- The US Dollar Index pulled back from a multi-year high.
- Gold futures consolidated in the recent range.
- Oil futures prices rallied through the week to a multi-month peak.
Key this week
Central Bank Watch: The main central bank activity this week is the People’s Bank of China Interest Rate Decision on Tuesday.
Macro Data Watch: The main macro data release this week is Global Flash PMI data on Friday. Some other releases of note are Chinese GDP on Monday, UK Employment reports on Tuesday and UK CPI on Wednesday.
Earnings Watch: The Q3 US earning season continues this week with Meta and Tesla (two of the Magnificent Seven) releasing their earnings on Wednesday.
| Date | Major Macro Data |
| 10/19/2026 | Chinese GDP, Industrial Production and Retail Sales; Canadian CPI |
| 10/20/2026 | PBoC Interest Rate Decision; German PPI; UK Employment Reports; US Building Permits, Housing Starts and Pending Home Sales |
| 10/21/2026 | Japanese Trade Report; UK CPI, PPI and RPI; German Buba Monthly Report |
| 10/22/2026 | US Initial Jobless Claims; EU Consumer Confidence |
| 10/23/2026 | UK Consumer Confidence and Retail Sales; Japanese CPI; Global Flash PMI; Canadian Retail Sales; US Consumer Inflation Expectation and Michigan Consumer Sentiment |
| Date | Major Earnings Data |
| 10/19/2026 | BHP Group Ltd |
| 10/20/2026 | SpaceX; GE Aerospace; Netflix; Rtx Group; ABB ADR; ABB; Intuitive Surgical; Chubb; Capital One Financial; 3M; United Airlines Holdings |
| 10/21/2026 | Meta Platforms; Tesla; Lam Research; Philip Morris; SAP ADR; Thermo Fisher Scientific; Texas Instruments; IBM; Abbott; NextEra Energy; Danaher; AT&T; Iberdrola SA ADR |
| 10/22/2026 | P&G; Roche Holding ADR; Nestle ADR; L’Oreal ADR; Union Pacific; Hermes International SA ADR; Blackstone; Spotify Tech; Barclays ADR |
| 10/23/2026 | Exxonmobil Holding; American Express; Safran SA ADR |
