Macroeconomic/ geopolitical developments
- US stocks finished mixed, with the Nasdaq gaining 0.45% while the S&P 500 and Dow fell 0.27% and 1.26% respectively. High Treasury yields and choppy oil prices continued to create uncertainty for investors.
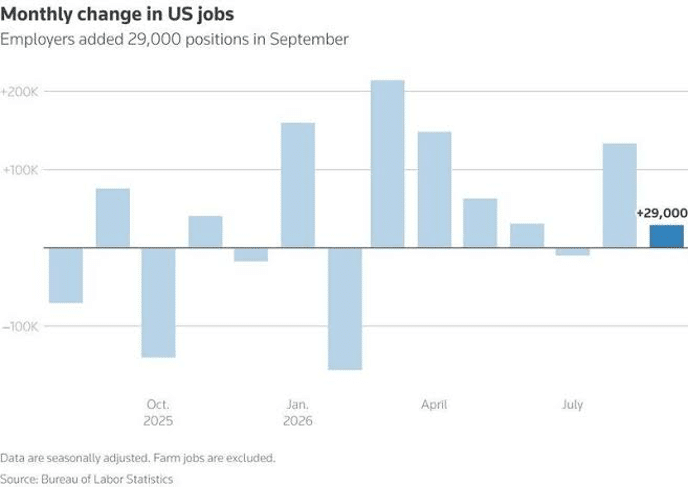
- The September jobs report showed a weaker labor market, with only 29,000 jobs added and unemployment rising to 4.2%. The softer data reduced expectations for another Federal Reserve rate increase in October.
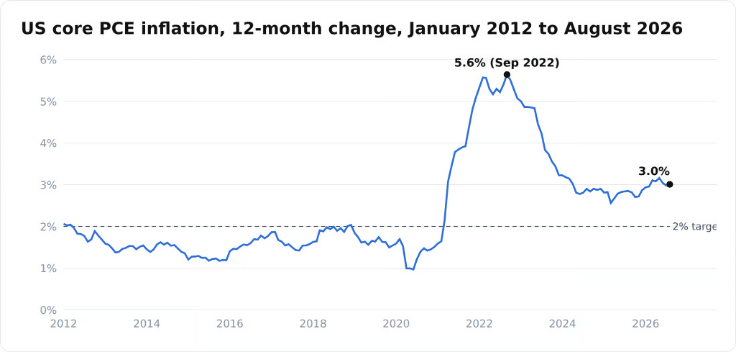
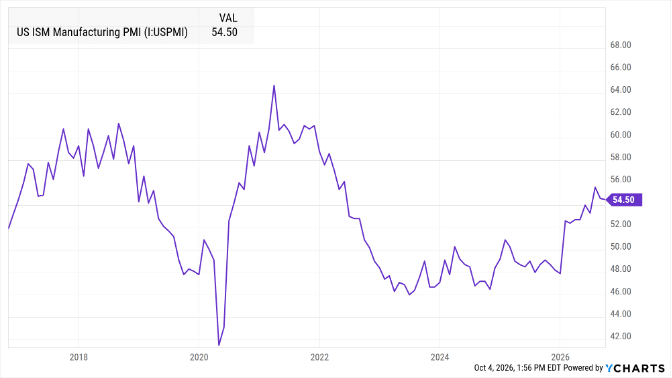
- PCE inflation came in below expectations, suggesting that underlying price pressures may be easing. Manufacturing PMI remained firmly in expansion, although rising input costs highlighted renewed inflationary pressure.
- Investors will focus on the Federal Reserve minutes for clues about the future path of interest rates following its latest increase. The September Services PMI will also be closely watched for signs of resilient demand, employment trends and continued cost pressures.
Global financial market developments
- US and global equity averages were mixed on the week.
- US and European bond yields were slightly higher on the week.
- The US Dollar Index moved to a multi-month high.
- Gold futures hovered near a multi-week low.
- Oil futures prices were choppy, little changed on the week.
Key this week
Central Bank Watch: The main central bank activity this week is the FOMC Minutes on Wednesday.
Macro Data Watch: The main macro data release this week is the Global Service and Composite PMI on Monday. Some other releases of note are the EU Retail Sales on Tuesday, Canadian Employment report and Michigan Consumer Sentiment Index both on Friday.
| Date | Major Macro Data |
| 10/05/2026 | Global Service and Composite PMI; EU Sentix Investor Confidence and PPI |
| 10/06/2026 | German Factory Orders; EU Retail Sales |
| 10/07/2026 | FOMC Minutes; German Industrial Production |
| 10/08/2026 | US Initial Jobless Claims |
| 10/09/2026 | Canadian Employment Report; US Michigan Consumer Sentiment Index and Consumer Inflation Expectations |
